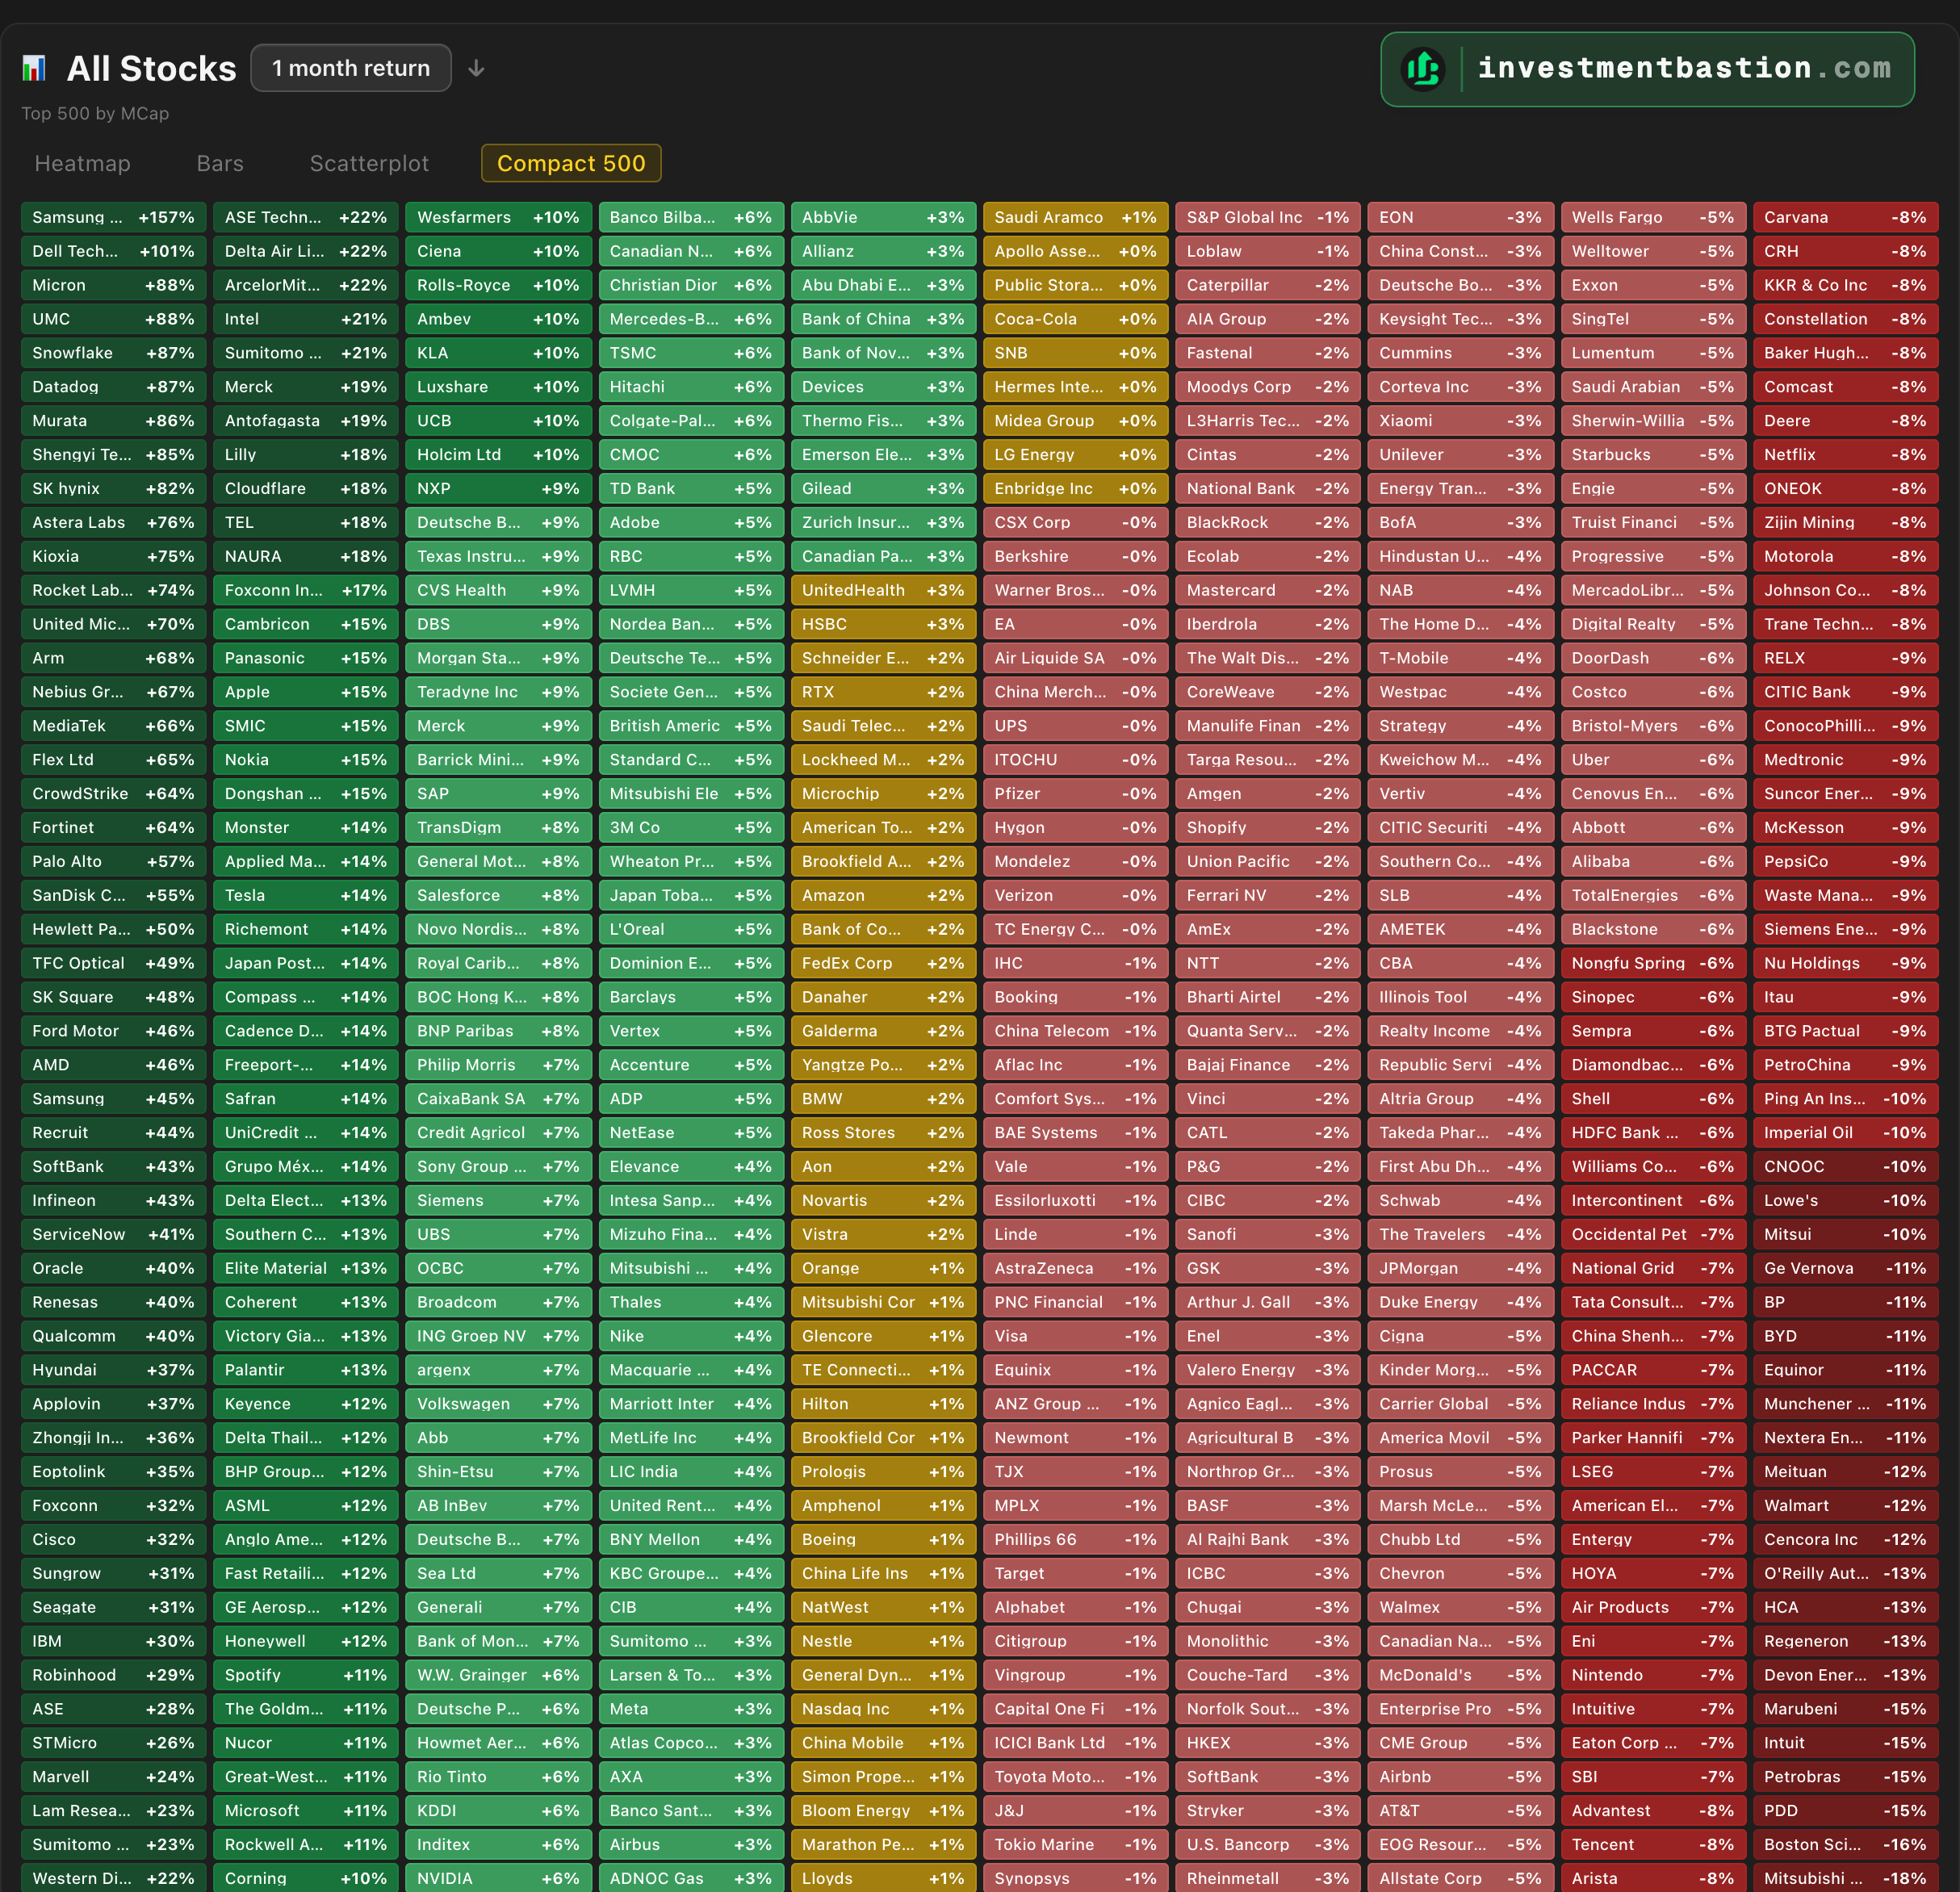
3 of the 10 best-performing large caps over the past month make memory chips. The HBM supercycle continues.
1. Memory is carrying the whole top.
Four of the top twelve are memory and storage makers: 🇰🇷 Samsung +157%, 🇺🇸 Micron $MU +88%, 🇰🇷 SK hynix +82%, 🇯🇵 Kioxia +75%. They move in lockstep because the driver is the same: HBM/DRAM/NAND pricing supercycle feeding AI datacenters.
2. Asia is beating the US in hardware.
The top of the board belongs to Korea, Taiwan, and Japan: 🇰🇷 Samsung +157%, 🇰🇷 SK hynix +82%, 🇯🇵 Murata +86%, 🇹🇼 UMC $UMC +88%, 🇯🇵 Kioxia +75%, 🇹🇼 MediaTek +66%. The US mega caps look quiet next to them, 🇺🇸 NVIDIA $NVDA around +6%, 🇺🇸 Apple $AAPL +15%. The gains moved up the supply chain, toward the companies making the chips and components rather than the end-brands.
3. The rally is narrow.
Leaders ran up tens of percent, but the median sits near zero. Banks, staples, healthcare, and telecom are flat or down. A handful of semis and AI software names are doing the heavy lifting, with no broad participation behind them.
4. Money left defense, oil, and China.
The laggards cluster tightly: oil (🇧🇷 Petrobras $PBR −15%, 🇬🇧 BP $BP −11%, 🇳🇴 Equinor $EQNR −11%, 🇨🇳 CNOOC −10%), Chinese tech (🇨🇳 PDD $PDD −15%, 🇨🇳 Meituan −12%, 🇨🇳 BYD −11%, 🇨🇳 Alibaba $BABA −9%, 🇨🇳 Tencent −7%), staples (🇺🇸 Walmart $WMT −12%, 🇺🇸 PepsiCo $PEP −9%, 🇺🇸 Costco $COST −6%), and healthcare (🇺🇸 Regeneron $REGN −13%, 🇺🇸 HCA $HCA −13%). A textbook risk-on month, capital rotating out of defensives into AI beta.