Adobe: The Market Is Pricing In an Apocalypse. The Numbers Tell a Different Story.
Adobe $ADBE stock has dropped roughly 30% over the past year, putting it in the bottom 1% by price momentum. The narrative driving the selloff is straightforward: AI is coming for Creative Cloud, and Adobe's moat is crumbling. But is the market right, or is it overreacting?
Why the Stock Is Down?
Several factors converged to crush Adobe's valuation.
AI disruption fears. Tools like Canva, Figma, Midjourney, and Runway are chipping away at workflows that used to require the full Creative Cloud suite. CIO surveys confirm the trend: enterprise IT budgets are actively shifting away from Adobe toward cheaper, AI-native alternatives. Why pay $60/month for Creative Cloud when a specialized AI tool does 80% of the job for $20?
Seat compression. AI makes individual designers 2–3x more productive. Companies need fewer licenses to get the same output. Fewer seats means less revenue for Adobe, even if total creative work stays the same.
Regulatory headwinds. A $150 million DOJ settlement over deceptive subscription practices and a UK investigation into cancellation fees added reputational damage to the mix.
Multiple compression. Adobe's forward P/E has collapsed to around 10x. The market has re-rated the stock from a high-growth compounder to a slow-growth utility. That's a brutal shift for a company that still delivers double-digit revenue growth.
The Threats Are Real, But Nuanced
Let's be honest: the competitive pressure is genuine.
AI-native tools are democratizing design. Canva now lets non-designers produce professional-quality content. Specialized tools for video generation (Runway, Pika), image creation (Midjourney), and UI design (Figma AI) are each carving out pieces of Adobe's territory. And generative AI is undermining the stock photography market. Why buy from Adobe Stock when you can generate exactly what you need?
Enterprise customers notice. CIOs are questioning whether full Creative Cloud subscriptions are justified when focused tools cost a fraction of the price.
But here's the other side: Adobe is not standing still.
The Bull Case No One Wants to Hear
Firefly is gaining real traction. Adobe's generative AI platform has produced $400 million in direct revenue. 75% of Fortune 500 companies have adopted it. In Q1 FY2026, 78% of enterprise contract renewals included paid Firefly AI credits, up from 52% just one quarter earlier. Usage nearly doubled, from 180 to 340 credits per active user per month.
Revenue keeps growing. Q1 FY2026 came in at $6.4 billion, up 12% year-over-year. Full-year FY2025 was a record $23.77 billion. This is not a company in decline.
Document Cloud is accelerating. The Acrobat and PDF business, including e-signatures, is growing at 16–18% annually, outpacing Creative Cloud. PDF remains the world's document standard, and AI-powered document workflows (Acrobat AI Assistant) are expanding the addressable market, not shrinking it.
The subscription moat is deep. 93% of revenue is recurring. Adobe has ecosystem lock-in through industry-standard file formats (PSD, AI, PDF, INDD), decades of professional training, enterprise compliance requirements, and deep integrations. Companies don't switch creative infrastructure in a quarter.
What the Consensus Actually Says
Here's where it gets interesting. While the stock price screams crisis, analyst consensus forecasts tell a completely different story.
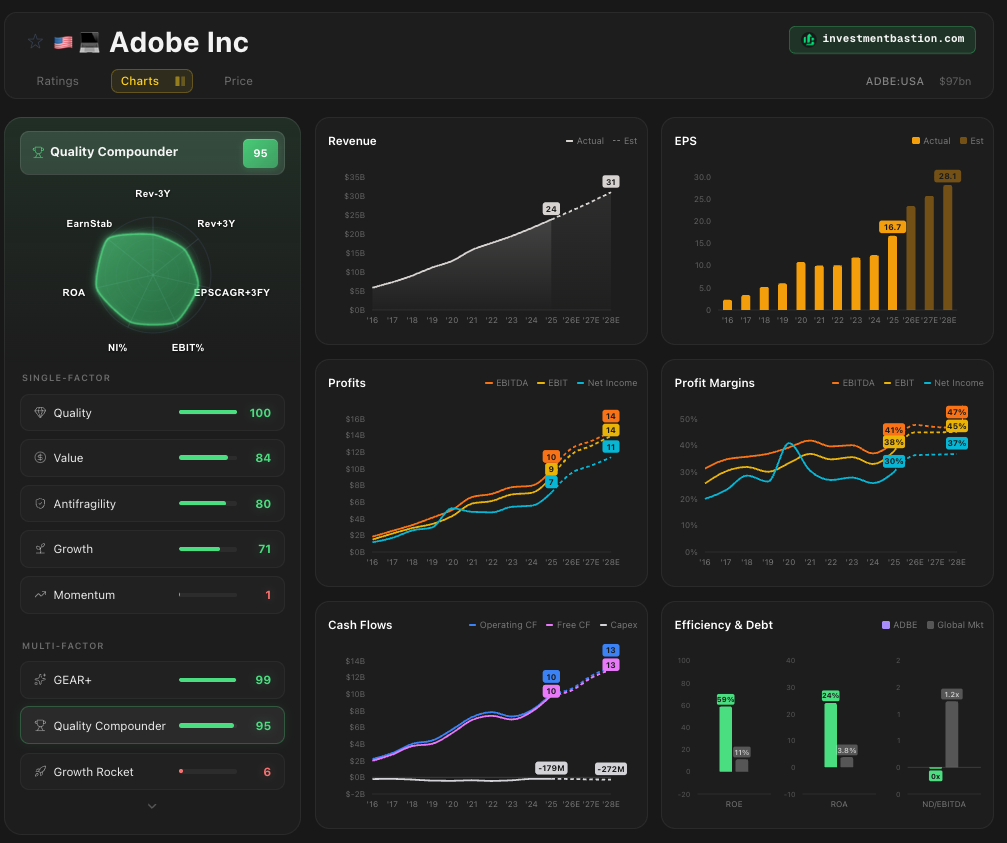
Revenue is expected to reach approximately $28.4 billion by FY2027, roughly +30% over three years. This estimate hasn't declined over the past year. It has actually inched higher.
Expected net profit margin is projected to expand from 30% to 37%, driven by AI-powered efficiency gains and operating leverage.
EPS is forecast to nearly double from current levels by FY2028.
Yet the forward P/E sits at around 10x, a level that prices in stagnation, not 30% revenue growth.
Bottom Line
The market is treating Adobe like a company on the verge of obsolescence. The financials say otherwise. Yes, the competitive landscape has permanently changed, and Adobe is no longer the only game in town. But "more competition" and "business collapse" are very different things.
Adobe's Creative Cloud is under pressure. Its Document Cloud is thriving. Its AI monetization is accelerating faster than most investors realize. And the stock is priced as if none of that matters.
A comeback is still very much in play.