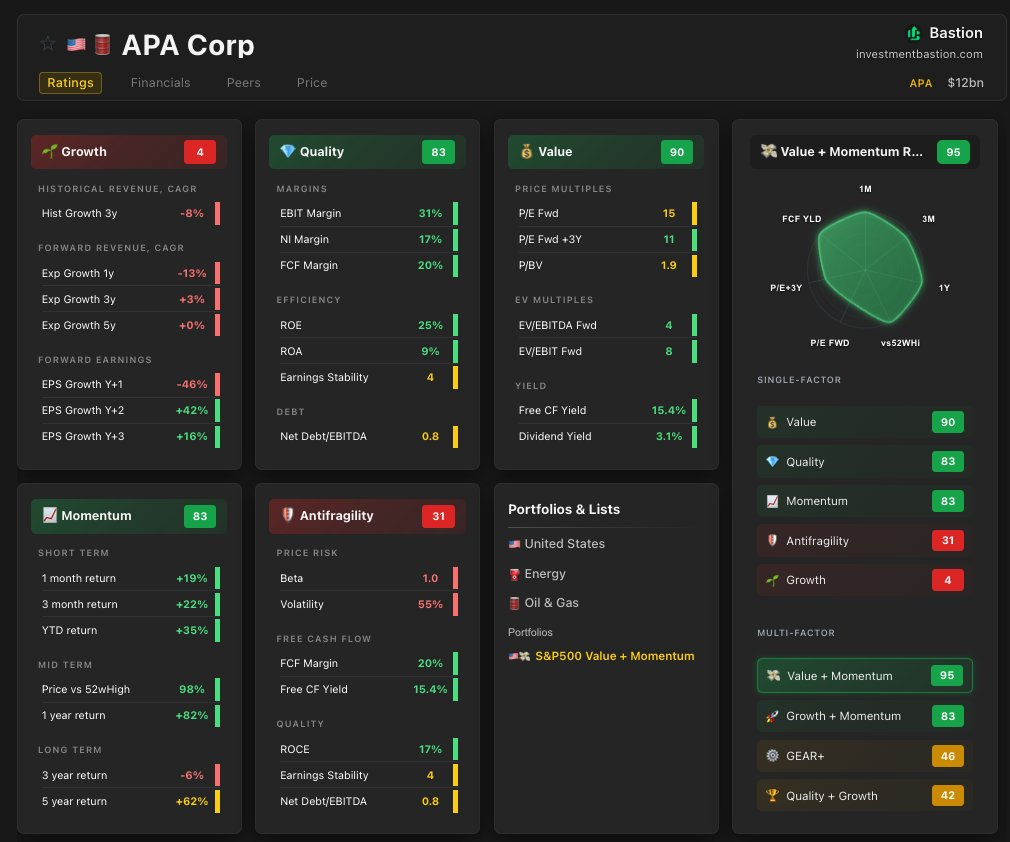
APA Corp: 15% FCF Yield, 7x Earnings, and an Iran Tailwind
Strategy: S&P 500 Value + Momentum
APA Corporation $APA is an oil and gas exploration and production company operating across four key regions:
Permian Basin (US) - the core asset. The 2024 acquisition of Callon Petroleum for ~$4.5B significantly expanded APA's footprint across the Delaware and Midland sub-basins.
Egypt (Western Desert) - a major international operation. Following a new gas pricing agreement, APA has shifted its Egypt strategy toward gas-weighted drilling.
Suriname (Block 58, offshore) - the strategic growth project. APA and TotalEnergies reached FID on the $10.5B GranMorgu deepwater development. First oil is expected in mid-2028, with a target capacity of 220,000 bbl/day.
United Kingdom (North Sea) - mature, legacy assets.
Why It's Cheap?
APA is one of the cheapest stocks in the S&P 500 on a multiples basis. The company trades at ~7x P/E with a ~15% FCF yield, generating $1.1B in annual free cash flow, even in a weak oil price environment.
The stock dropped over 50% from its 2024 highs. The market punished APA for the Callon Petroleum acquisition, an all-stock deal that increased leverage and diluted shareholders.
Why It May Not Stay Cheap?
The Iran conflict has triggered the most significant oil supply shock in decades. APA is a direct beneficiary:
Western Hemisphere production. The bulk of APA's output comes from the Permian Basin and Suriname (future), far from the disruption zone. As Middle Eastern supply becomes uncertain, Western Hemisphere barrels gain a structural premium.
High operating leverage to oil prices. Every $10 increase in Brent translates to hundreds of millions in additional free cash flow. At $80+ Brent, APA's current valuation looks deeply mispriced relative to its cash generation.
Egypt is a manageable risk. APA's Egyptian operations sit in a geopolitically sensitive region, but they have not been directly impacted so far. The risk is worth monitoring, not pricing in as a certainty.
At current oil prices above $80, APA's ~7x earnings multiple implies the market still expects a return to structurally low commodity prices. If that assumption is wrong, the upside is substantial.