April 7, 2026
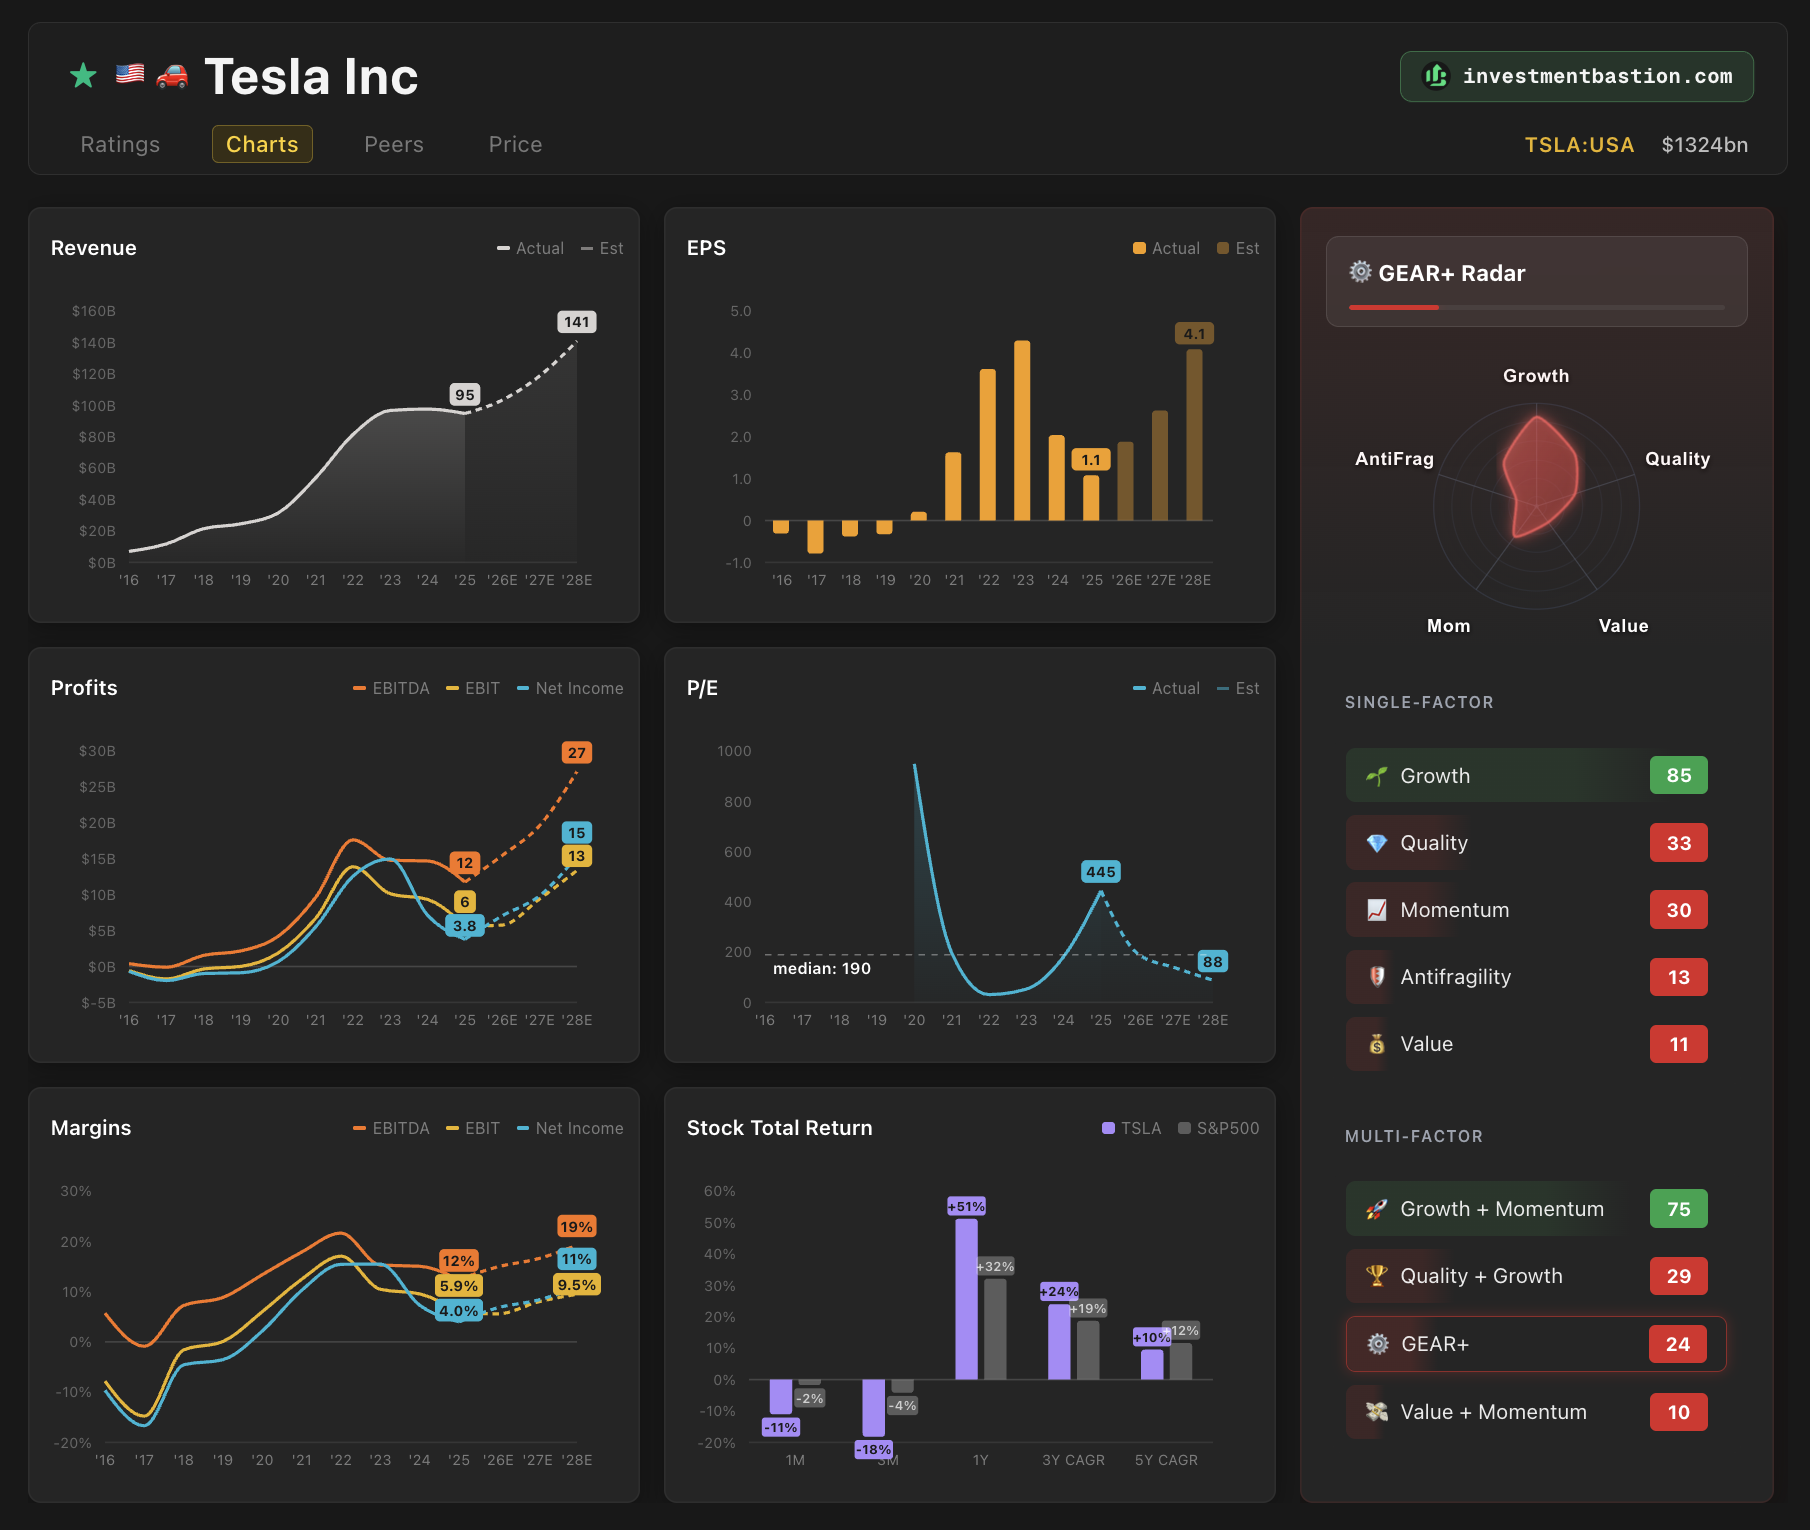
JPMorgan is warning Tesla stock may crash 60%. This dashboard shows why.
According to consensus estimates, Tesla is not expected to return to its 2023 profit levels within the next 3 years. $TSLA
Yet the market still values the company at ~200x forward earnings, ~9x more expensive than the broader US stock market.
What supports this valuation? Expectations of super growth 5 to 10 years out: robotaxis, Optimus, energy. All of which remain beyond the horizon of analyst forecasts.
The GEAR+ Radar in Bastion Terminal illustrates this well: Growth is 85, but Quality is just 33 and Value is 11. Strong growth, but you pay a very steep price for it. Bastion's strategies don't favor assets like this. Too many expectations baked in, too little margin of safety.