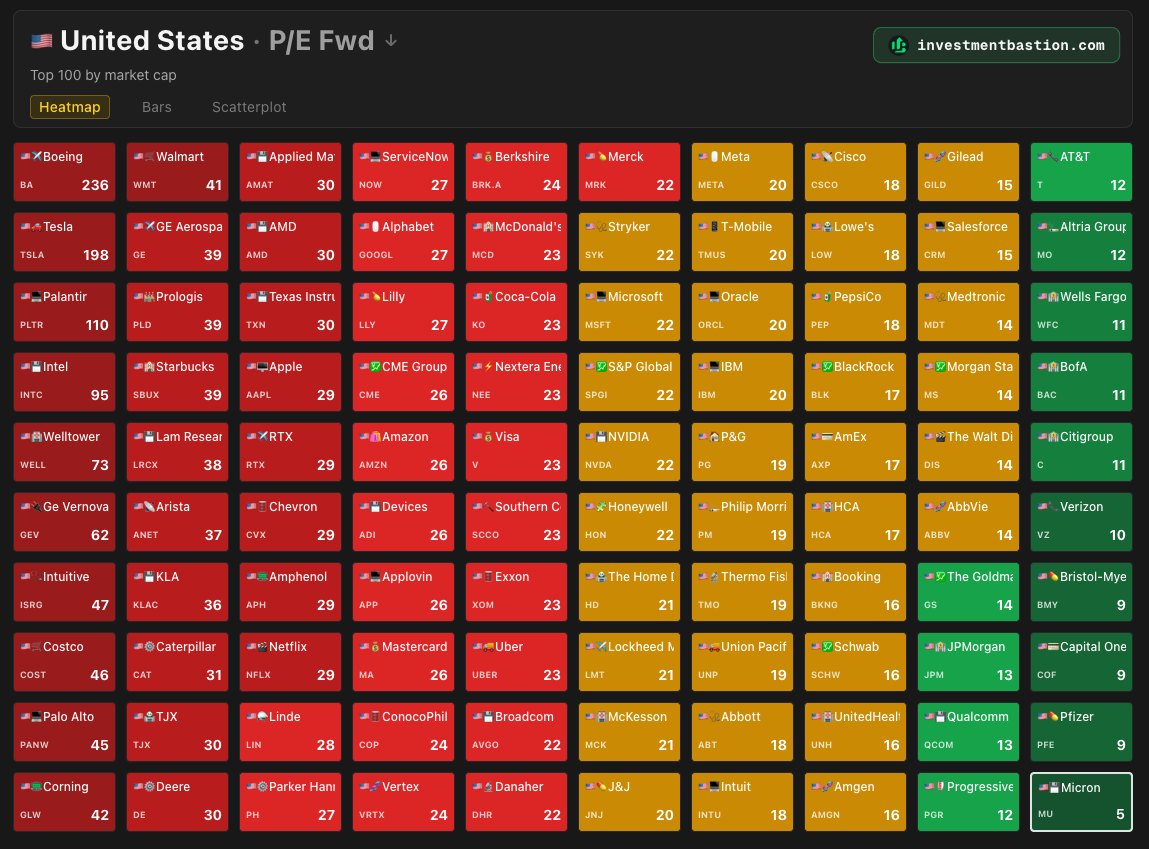
Micron is the cheapest stock in the US Top 100 by Forward P/E - just 5x.
Why? $MU
1. Peak-of-cycle earnings. This is the #1 reason. Memory (DRAM & NAND) is one of the most cyclical businesses in tech. Micron's earnings are currently inflated by the AI boom and HBM (High Bandwidth Memory) demand. A low P/E on peak earnings is the classic cyclical trap.
2. Commodity product, no moat. Unlike NVIDIA or ASML, Micron sells what is essentially a commodity. DRAM and NAND chips are interchangeable across suppliers (Samsung, SK Hynix). When supply catches up to demand, pricing power evaporates.
3. Massive capex requirements. Memory fabs cost billions. Micron is spending ~$8-14B/year on capex. Even when revenue is booming, free cash flow can lag significantly behind reported earnings.
4. AI demand may not be permanent. The current HBM supercycle is real, but the market is questioning how long it lasts. If hyperscaler capex slows down, Micron's HBM revenues could plateau.
5. History repeats. Micron has traded at 4-7x forward P/E at every cycle peak for the past 20 years. Each time, "this time is different" (5G, cloud, crypto, now AI). Each time, the cycle turned.
The stock is in Bastion's Growth portfolio and will likely return to Bastion's Value portfolio as well. That said, it never hurts to take a critical look at your key holdings.