April 27, 2026
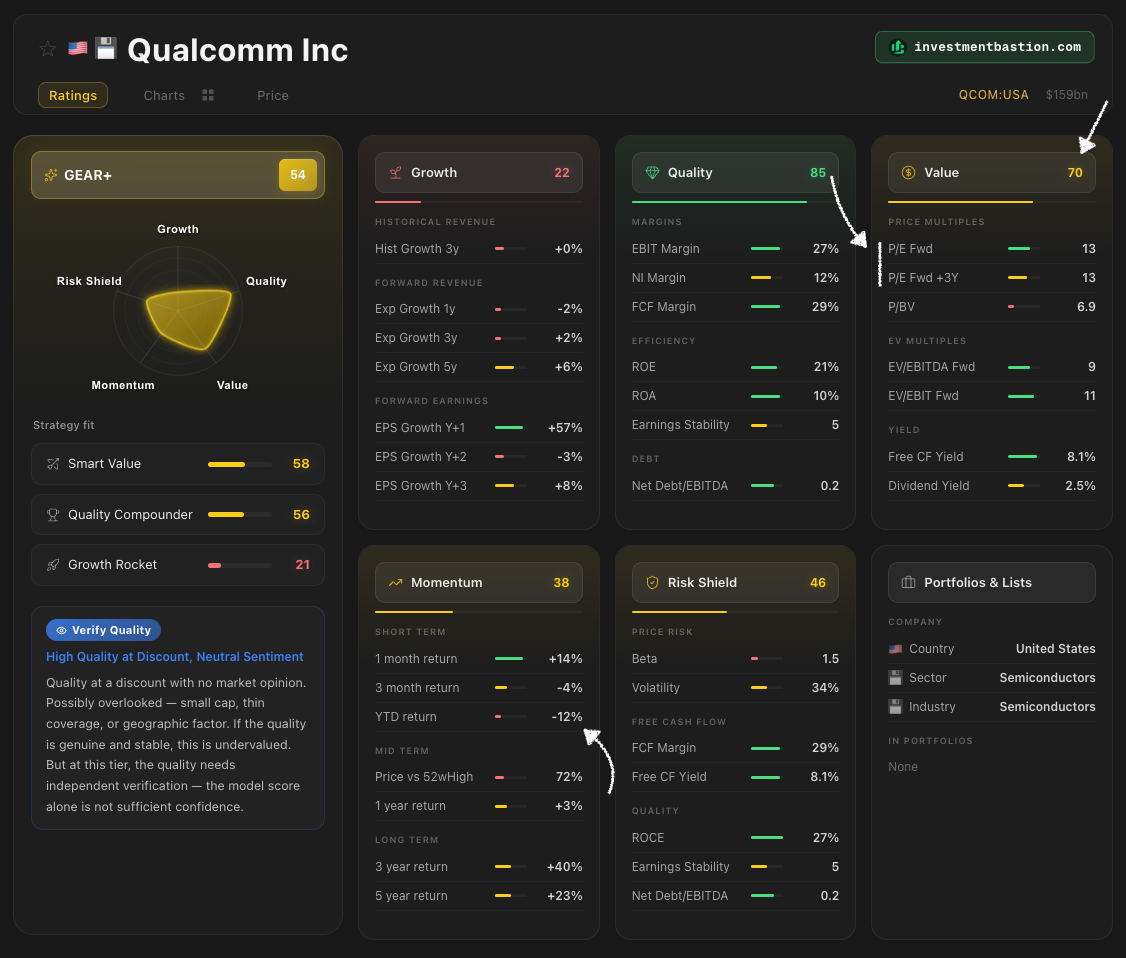
Qualcomm is the only major semiconductor stock in the red YTD. Why?
Memory makers (Micron, SK Hynix) shifted production to High-Bandwidth Memory for AI data centers. Result: acute shortage of LPDDR5X mobile memory needed to build smartphones.
The paradox: Qualcomm $QCOM chips (Snapdragon) are ready, but key customers (Xiaomi, OPPO, vivo) can't assemble devices. No memory, no phones.
70% of Qualcomm revenue = smartphone chips. Memory shortage hits its core market directly.
Now Qualcomm is one of the cheapest semis. Value Score 70/100. Fwd P/E 13x.
Not in Bastion portfolios. But smartphone production normalization next year could significantly upgrade its Smart Value rating.